Business · United States of America
Bessent expects Treasury yields to fall after 10-year rate tops 5%
The Treasury secretary acknowledged that he cannot control the bond market but argued that yields should decline over time. The comments followed a rise in government borrowing costs and scrutiny of the expanding interest bill.
Bessent said the Treasury market was beyond his control, while maintaining that yields would decline over time. The 10-year yield has crossed 5%, intensifying scrutiny of US interest costs.
- Bessent acknowledged the market is beyond his control.
- He still expects bond yields to decline over time.
- The 10-year Treasury yield crossed 5%.
- Federal interest expenses are projected to keep rising.
- Analysts disagree over the immediacy of fiscal risks.
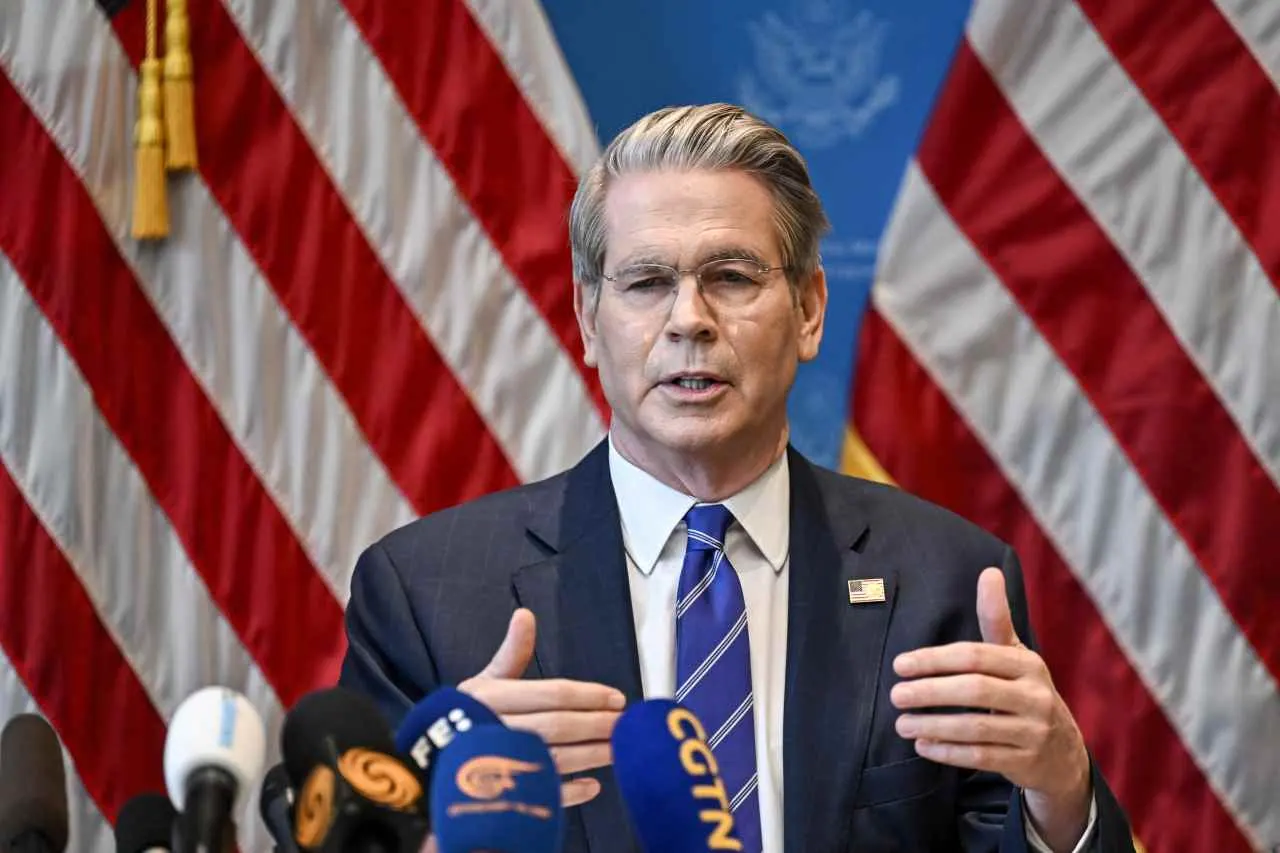
What's new
- Bessent acknowledged limits on his control of the Treasury market.
- He argued that US bond yields would eventually decline.
- The 10-year Treasury yield crossed 5%, according to CNBC.
Treasury Secretary Bessent said in an Axios interview reported on Oct. 4 that he could not control the US Treasury market, while maintaining that bond yields would decline over time. The televised interview followed a rise in the benchmark 10-year Treasury yield beyond 5%, according to CNBC.123
A retreat from an earlier declaration
Bessent’s acknowledgment marked a change in emphasis from his earlier declaration, “I am the house.” MarketWatch reported that he had made that statement a month before the Axios interview and subsequently walked it back while defending the Treasury Department’s record in the bond market.3
The yield on the benchmark 10-year Treasury crossed 5% on Oct. 5 and remained firmly above that level, CNBC reported. The outlet also said US government borrowing costs had reached their highest levels in decades.1
The government’s rising interest bill
CNBC reported that the federal government’s net interest costs were estimated at about $1.05 trillion during the first 11 months of fiscal 2026. TD Securities projected annual interest costs of around $1.1 trillion with rates still high, rising to $1.4 trillion in 2027, $1.5 trillion in 2028 and $1.6 trillion in 2029 if yields remained close to present levels.1
The effect of higher yields would develop as existing securities mature and the government issues new debt. The weighted-average maturity of US government debt is about 5.9 years, while the average interest rate on the debt is about 3.4%, according to CNBC. The average coupon excluding Treasury bills is 3.1%.1
The Congressional Budget Office projected federal debt held by the public at about 101% of gross domestic product in fiscal 2026. Meanwhile, the Bureau of Economic Analysis put second-quarter nominal GDP growth at an 8.5% annualised pace. CNBC reported that the government’s average interest rate remained below nominal economic growth.1
Warnings and counterarguments
Maya MacGuineas, who leads the Committee for a Responsible Federal Budget, cautioned that higher borrowing costs could set off a cycle where interest payments lead to more borrowing. “The real threat is the debt spiral,” she said. “If interest begets debt, and debt begets interest, eventually debt will spin out of control.”1
Gennadiy Goldberg and Molly Brooks, strategists at TD Securities, offered a less immediate assessment, saying: “A fiscal apocalypse is not upon us just yet.” That conclusion is reported by only one source in the dossier and is classified there as disputed. Matthew Reese, L&G Asset Management's head of global bond strategies, also argued that concerns about a near-term US fiscal crisis were overstated.1
The TD analysis pointed to Japan as an example of a country that had managed higher debt levels alongside very low nominal growth without entering a fiscal crisis. Reese said the United States remained some distance from such a crisis, according to CNBC.1
What is pushing yields higher
CNBC attributed the increase in Treasury yields to a combination of stronger economic growth, expectations of Federal Reserve rate increases, higher oil prices, corporate bond issuance, repositioning by fast-moving investors and concern over the fiscal outlook. BMO Capital Markets described the increase in longer-term yields as largely driven by real, or inflation-adjusted, rates.1
A BMO survey found that housing was the area most respondents expected to show strain first from rising real rates, followed by stocks and corporate credit. BMO’s analysis said a lasting limit on further increases in yields would require clear evidence that the economy or risk assets were weakening under higher borrowing costs.1
Why it matters
For readers in Europe, the central issue is whether the Treasury-market move represents a manageable repricing or the beginning of a worsening US debt-and-interest cycle. Bessent’s comments also underline the limits of a Treasury secretary’s ability to direct market yields even while defending the government’s record and forecasting lower rates.123
Related stories
Version history
- version 1 ·